What is PAYE?
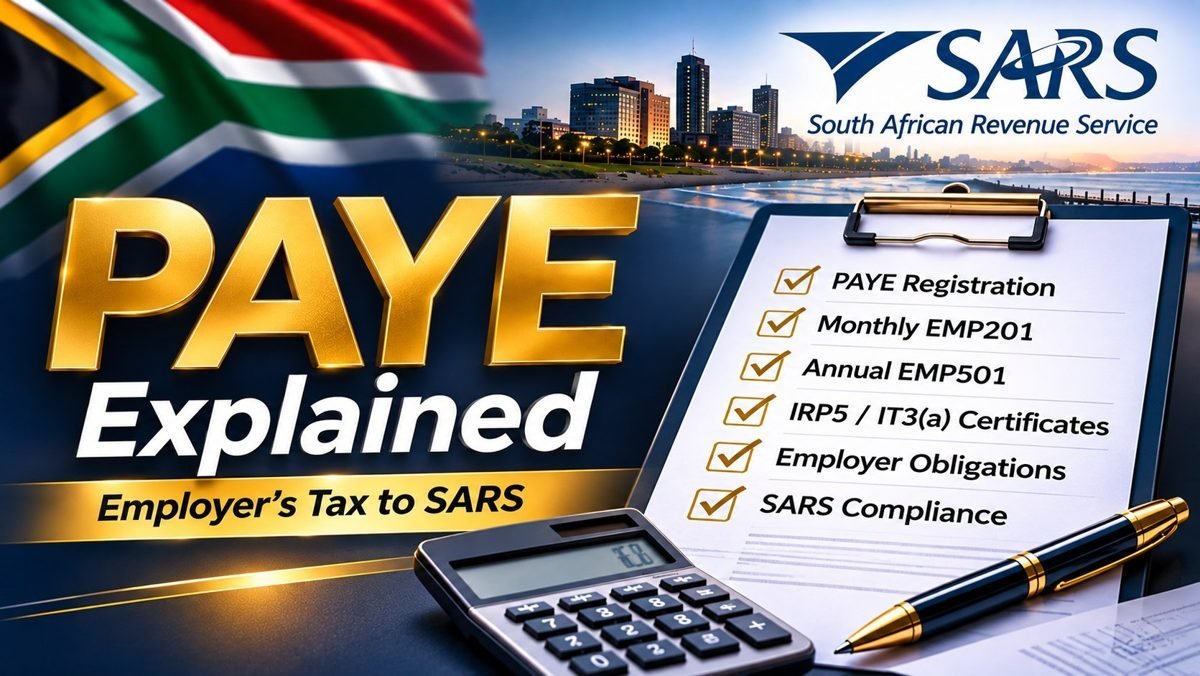
PAYE is not a separate tax — it is the employee’s income tax, collected in advance through payroll. The employer acts as SARS’ agent: it calculates the tax using the SARS tax tables, withholds it from salary or wages, and pays it to SARS.
Who must register?
- An employer must register with SARS for employees’ tax when it pays remuneration to an employee who is liable for tax.
- Registration must be done within 21 business days of becoming an employer.
- Directors of private companies are treated as employees for PAYE purposes.
How does it work each month?
- Calculate gross remuneration, including taxable benefits.
- Deduct PAYE using the SARS tax tables, together with UIF.
- Declare PAYE, UIF and SDL on the EMP201 and pay SARS by the 7th of the following month.
- Twice a year, reconcile everything on the EMP501 and issue IRP5 / IT3(a) certificates.
Records that matter
- Payslips and payroll reports
- Employee tax numbers and personal details
- EMP201 declarations and proof of payment
- EMP501 reconciliations and IRP5 / IT3(a) certificates
Common mistakes
- Not registering when the first employee starts
- Leaving taxable benefits (e.g. a company car or allowances) off the payroll
- Paying the EMP201 late, which attracts penalties and interest
- Payroll totals that do not match what was declared to SARS
When should you get professional help?
If you are employing your first staff, paying directors, providing benefits or allowances, or your payroll and SARS figures do not agree, get professional help.