Who contributes?
- Employers and employees in South Africa generally must contribute to UIF.
- It applies to employees who work more than 24 hours a month for the employer.
- Some categories of workers are excluded — check the position for your employees.
How much is it?
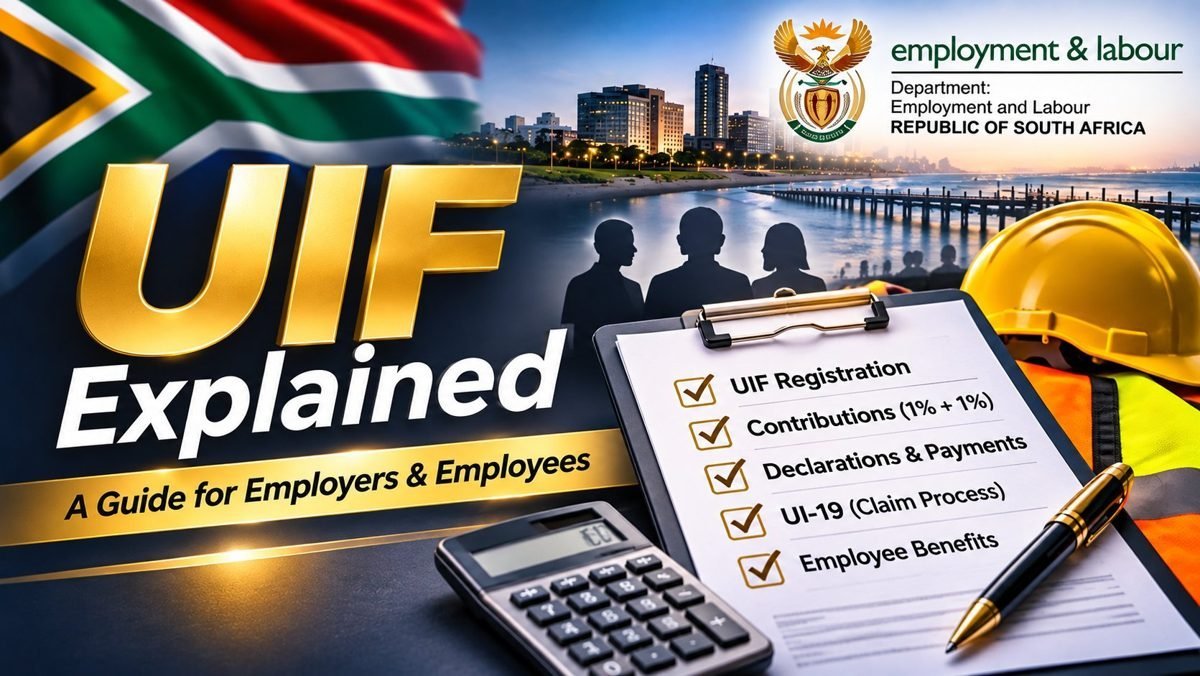
- 1% deducted from the employee’s remuneration, plus 1% paid by the employer.
- Calculated on remuneration up to R17,712 per month (the ceiling since 1 June 2021).
- So the maximum is R177.12 per month from the employee and R177.12 from the employer.
How is it paid?
Employers registered with SARS for PAYE or SDL declare and pay UIF together with PAYE on the monthly EMP201. Employers who are not registered with SARS for those taxes pay UIF directly to the Unemployment Insurance Fund. Employers must also keep employee information up to date with the Department of Employment and Labour.
A simple example
An employee earns R12,000 a month. The employer deducts R120 (1%) from the salary and adds its own R120, paying R240 for UIF with that month’s EMP201.
Common mistakes
- Not registering domestic or part-time employees who qualify
- Calculating UIF on earnings above the ceiling
- Not issuing UI-19 forms when employees leave, which delays their claims
When should you get professional help?
If you are unsure whether your workers must contribute, you employ part-time or domestic staff, or an employee cannot claim because records are wrong, get help.